
GoWind Quant
GoWind Quant is a quantitative research platform covering the full workflow of "market data → smart screening → strategy research → backtesting → paper trading". Market data, datasets, research, trading rehearsal, and AI assistance live in one workspace, so strategy research flows as smoothly as using a professional market terminal.
Core Highlights
- Data in one step: quotes, candlesticks, order book depth, and tick-by-tick trades on a single screen with real-time refresh — order book movements are visible immediately
- AI involved end to end: AI stock screening, AI strategy generation, AI backtest interpretation, and AI daily trading reports — natural language runs through the entire research workflow
- Realistic backtesting: real-world trading constraints such as price limits and trading halts are accounted for, with built-in slippage and commission models, making backtest results more trustworthy
- Portfolio strategies as first-class citizens: single-instrument and multi-instrument portfolio strategies share one workbench — define the universe, write cross-sectional logic in an on_bars callback, and manage risk and evaluation at the portfolio level
- Robustness checks built in: parameter optimization, walk-forward validation, and Monte Carlo confidence intervals — overfitting protection out of the box
- Risk-safe trading rehearsal: limit orders, stop-loss orders, an intraday loss circuit breaker, and daily reconciliation corrections keep risk controllable across the entire paper-trading chain
- Trustworthy, traceable data: multiple data sources cross-connected, with a data quality panel showing freshness and coverage per domain — every candlestick is traceable
Feature Overview
1. Market Data
| Feature | Description |
|---|---|
| Real-time market data | Quotes, candlesticks, order book depth, tick-by-tick trades, and index quotes in switchable tabs on one screen |
| Real-time order book push | Order book and tick data refresh in real time — no manual polling |
| Multi-source data access | Multiple mainstream data sources, including baostock, tushare, finnhub, eodhd, and marketstack |
| Data quality panel | Freshness grading, coverage, anomaly detection, multi-source cross-validation, and ingestion statistics across seven data domains — data trustworthiness at a glance |
| Data source health monitoring | Availability and collection status of each data source displayed centrally, so issues surface early |
2. News and Sentiment
| Feature | Description |
|---|---|
| Sentiment collection and analysis | Market news is collected automatically, with sentiment orientation analyzed automatically |
| Similar-news aggregation | Duplicate coverage of the same event is merged automatically — denoising with an audit trail |
| Sentiment alert delivery | Key sentiment items are pushed instantly to DingTalk, Feishu, and WeCom groups |
| AI daily trading report | The daily review is generated by AI and delivered proactively |
3. Smart Stock Screening
| Feature | Description |
|---|---|
| Condition-based screening | 8 price-volume and fundamental conditions combined freely for filtering |
| AI stock screening | Describe your screening idea in natural language and AI converts it into filter conditions |
| Watchlists and alerts | Manage a watchlist and get automatic alerts when target prices are reached |
| Scheduled screening | Screening plans run on a schedule with results ready before market open; hits and dropouts are notified proactively |
4. Strategy Research
| Feature | Description |
|---|---|
| Strategy authoring | Dual engines in Lua and JavaScript, with common indicators such as MACD, RSI, BOLL, ATR, and KDJ built in; single-instrument and multi-instrument portfolio modes |
| Portfolio strategies | Cross-sectional multi-instrument strategies: an on_bars callback receives the whole universe at once, instruments come from index constituents or a custom pool, with portfolio-level risk (such as a max-concurrent-holdings cap) and unified evaluation — one engine for backtest and rehearsal |
| News-event strategies | Subscribe to news alert events to trigger strategy execution — one more trigger source beyond market data |
| Factor system | 16 classic factors out of the box, with IC/IR analysis and layered backtesting; custom factor expressions supported |
| AI strategy generation | Describe a strategy idea in natural language and AI drafts the strategy, auto-validates it, and puts it to use |
| Python research SDK | Research data exports as pandas DataFrames, plugging seamlessly into your existing analysis environment |
5. Backtest Center
| Feature | Description |
|---|---|
| Realistic execution | Price adjustment (adjustment-factor handling), benchmark comparison, and market constraints such as price limits and trading halts |
| Parameter optimization | Grid-based parameter sweeps, walk-forward rolling validation, and optimization heatmaps |
| Robustness evaluation | Monte Carlo confidence intervals and tail-risk analysis to test strategy robustness |
| AI backtest interpretation | Backtest reports are interpreted automatically by AI for fast problem locating |
| Portfolio backtesting | Multi-instrument portfolio backtests with portfolio-level risk control and unified evaluation; portfolio strategies also support grid and walk-forward optimization, with per-instrument attribution on the equity curve page |
6. Paper Trading
| Feature | Description |
|---|---|
| Trading workbench | Order placement, positions, and funds in one screen |
| Order types | Limit and stop-loss orders; open orders are valid for the day and cancelled automatically at close |
| Risk-control circuit breakers | Built-in risk rules and circuit breakers halt anomalies automatically |
| Daily reconciliation | Automatic reconciliation and difference correction keep books aligned with positions |
| Portfolio overview | Funds and returns across multi-strategy portfolios, with concentration at a glance |
7. AI Assistant
| Feature | Description |
|---|---|
| Intelligent Q&A | Conversational Q&A grounded in platform data and research knowledge, with knowledge bases supported |
| Natural-language data queries | Query research data in plain language — no query syntax required |
| Scheduled data queries | Common data queries run on a schedule with results pushed proactively |
UI Preview
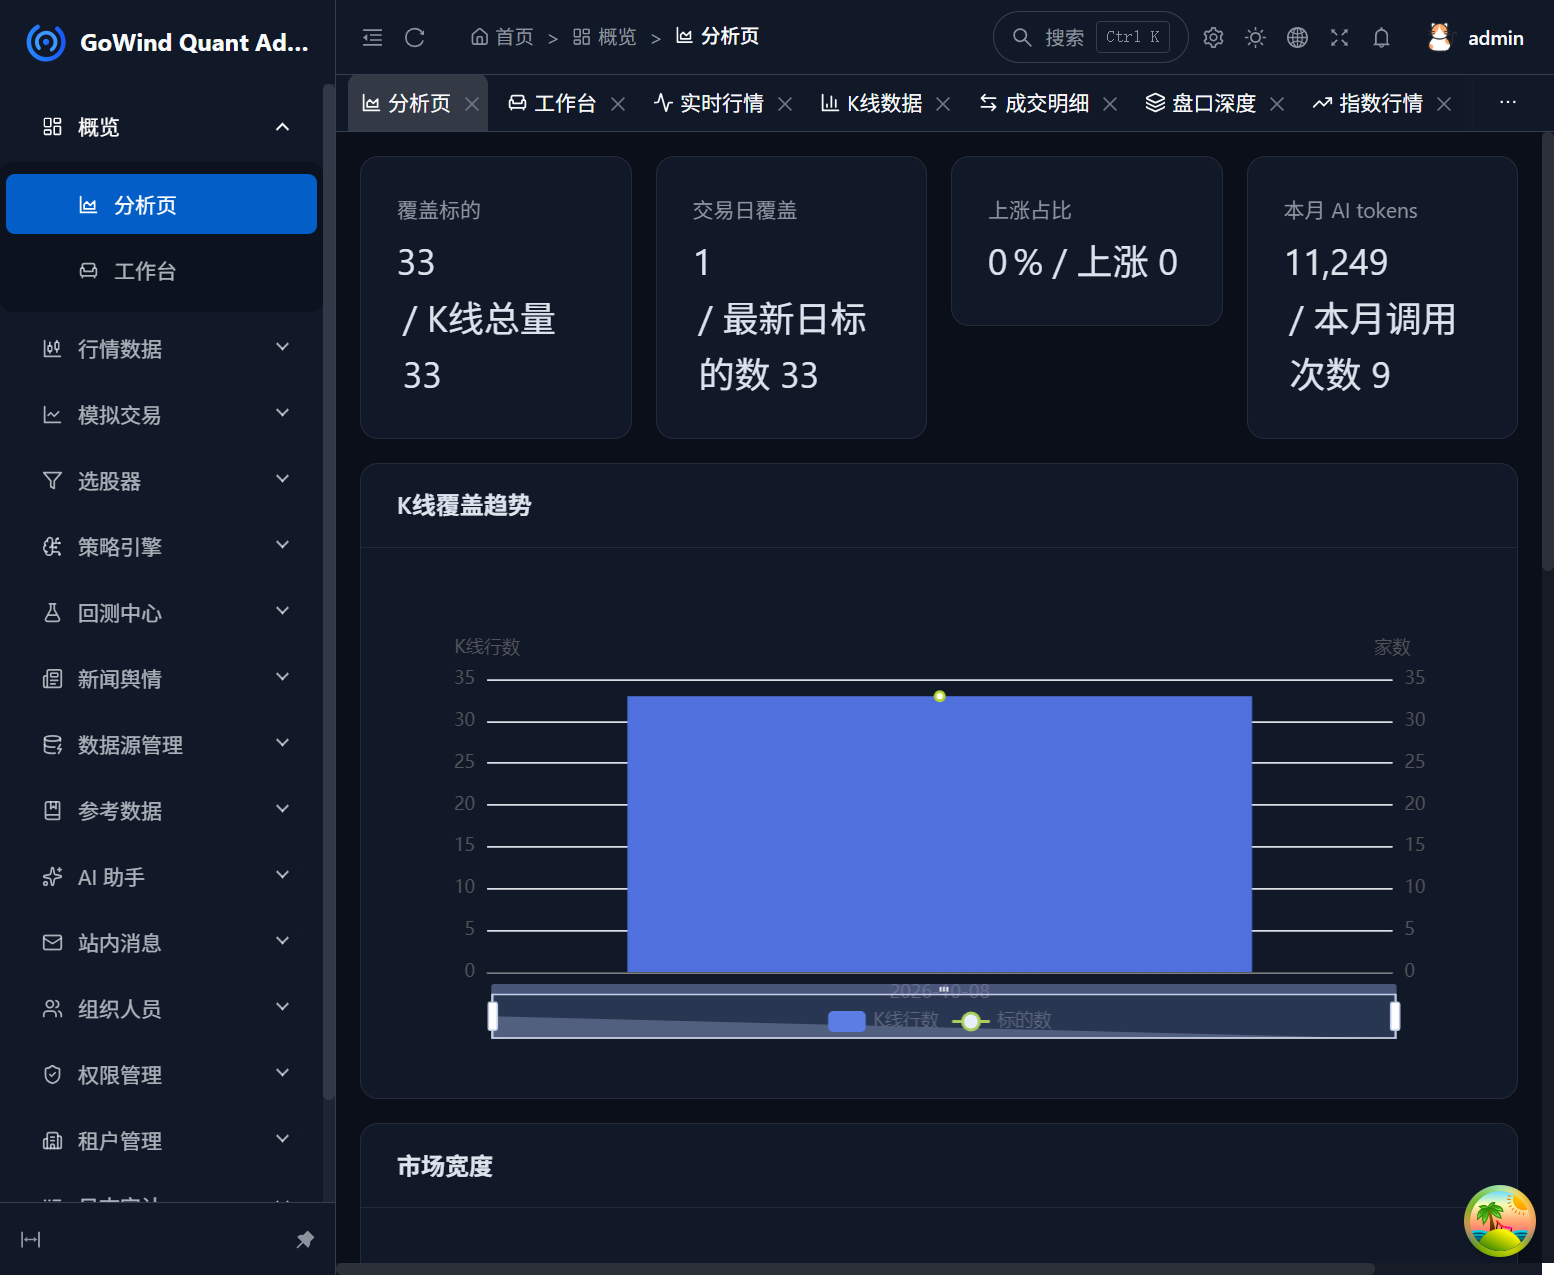 | 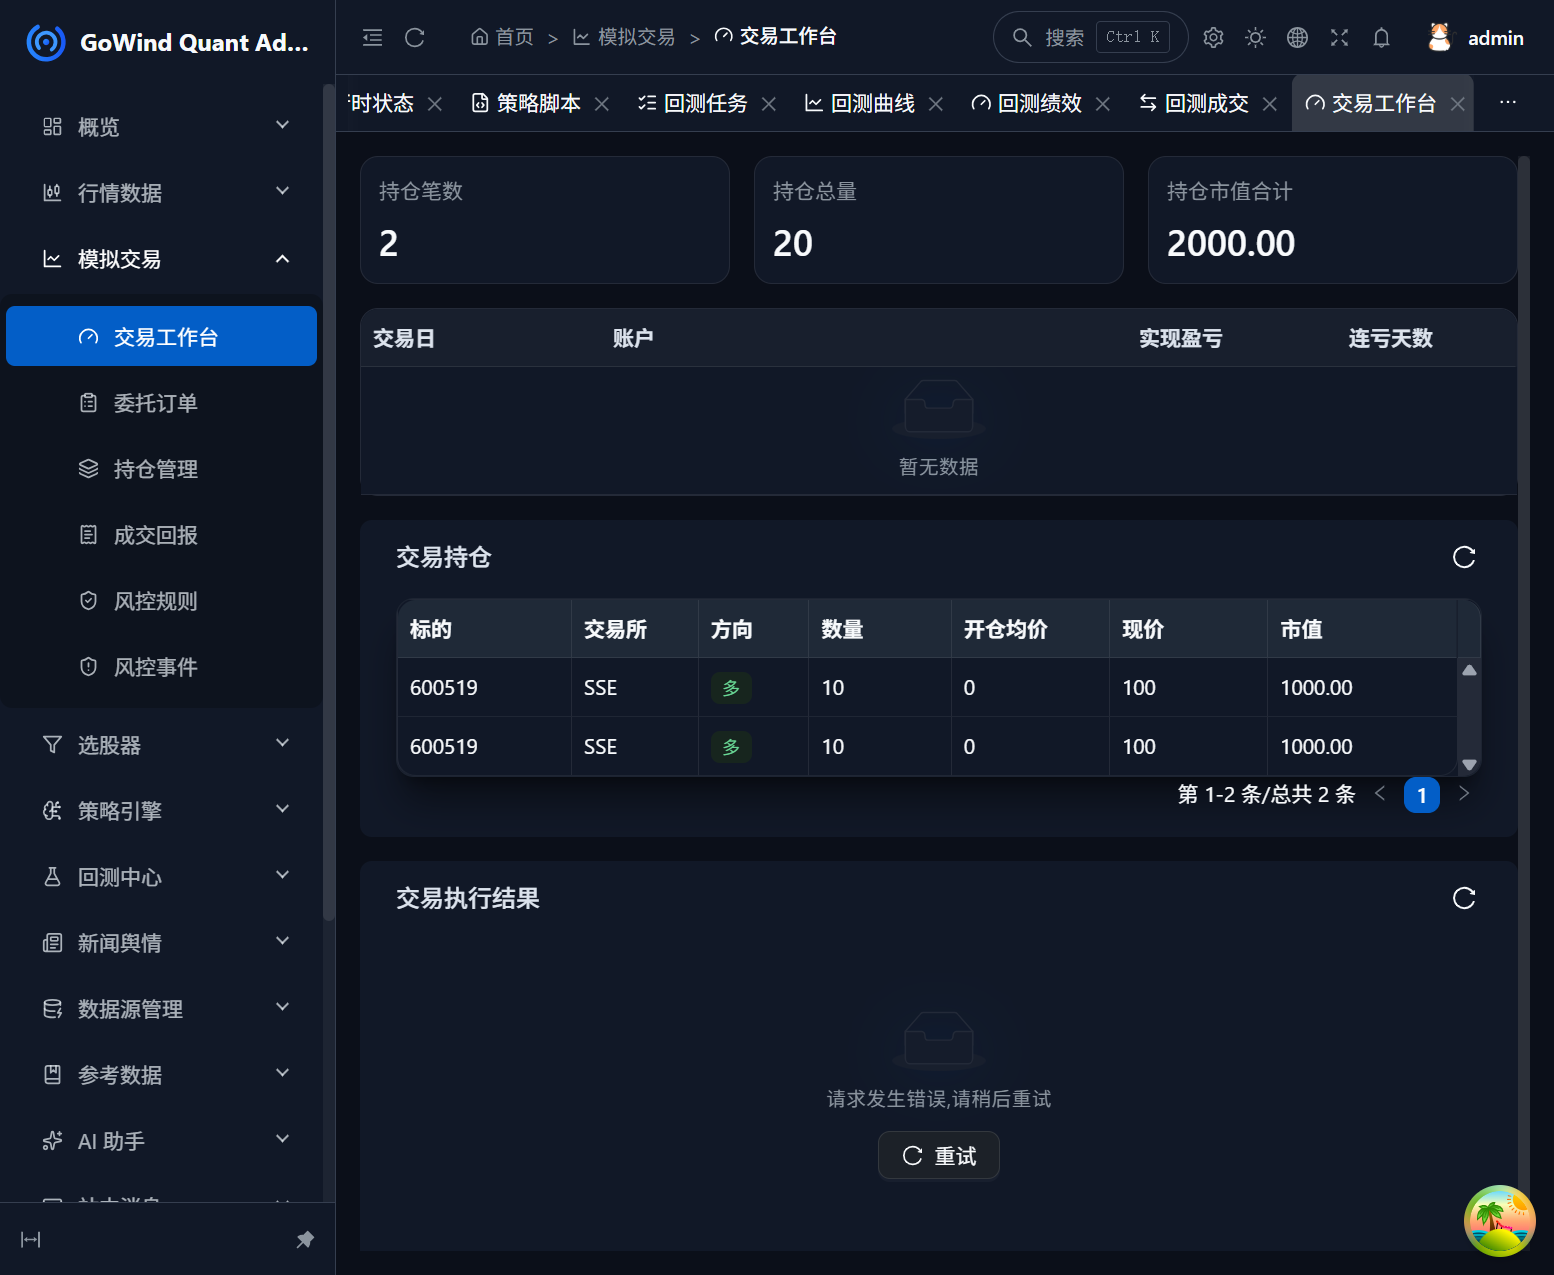 |
|---|---|
| Analytics dashboard | Trading workbench |
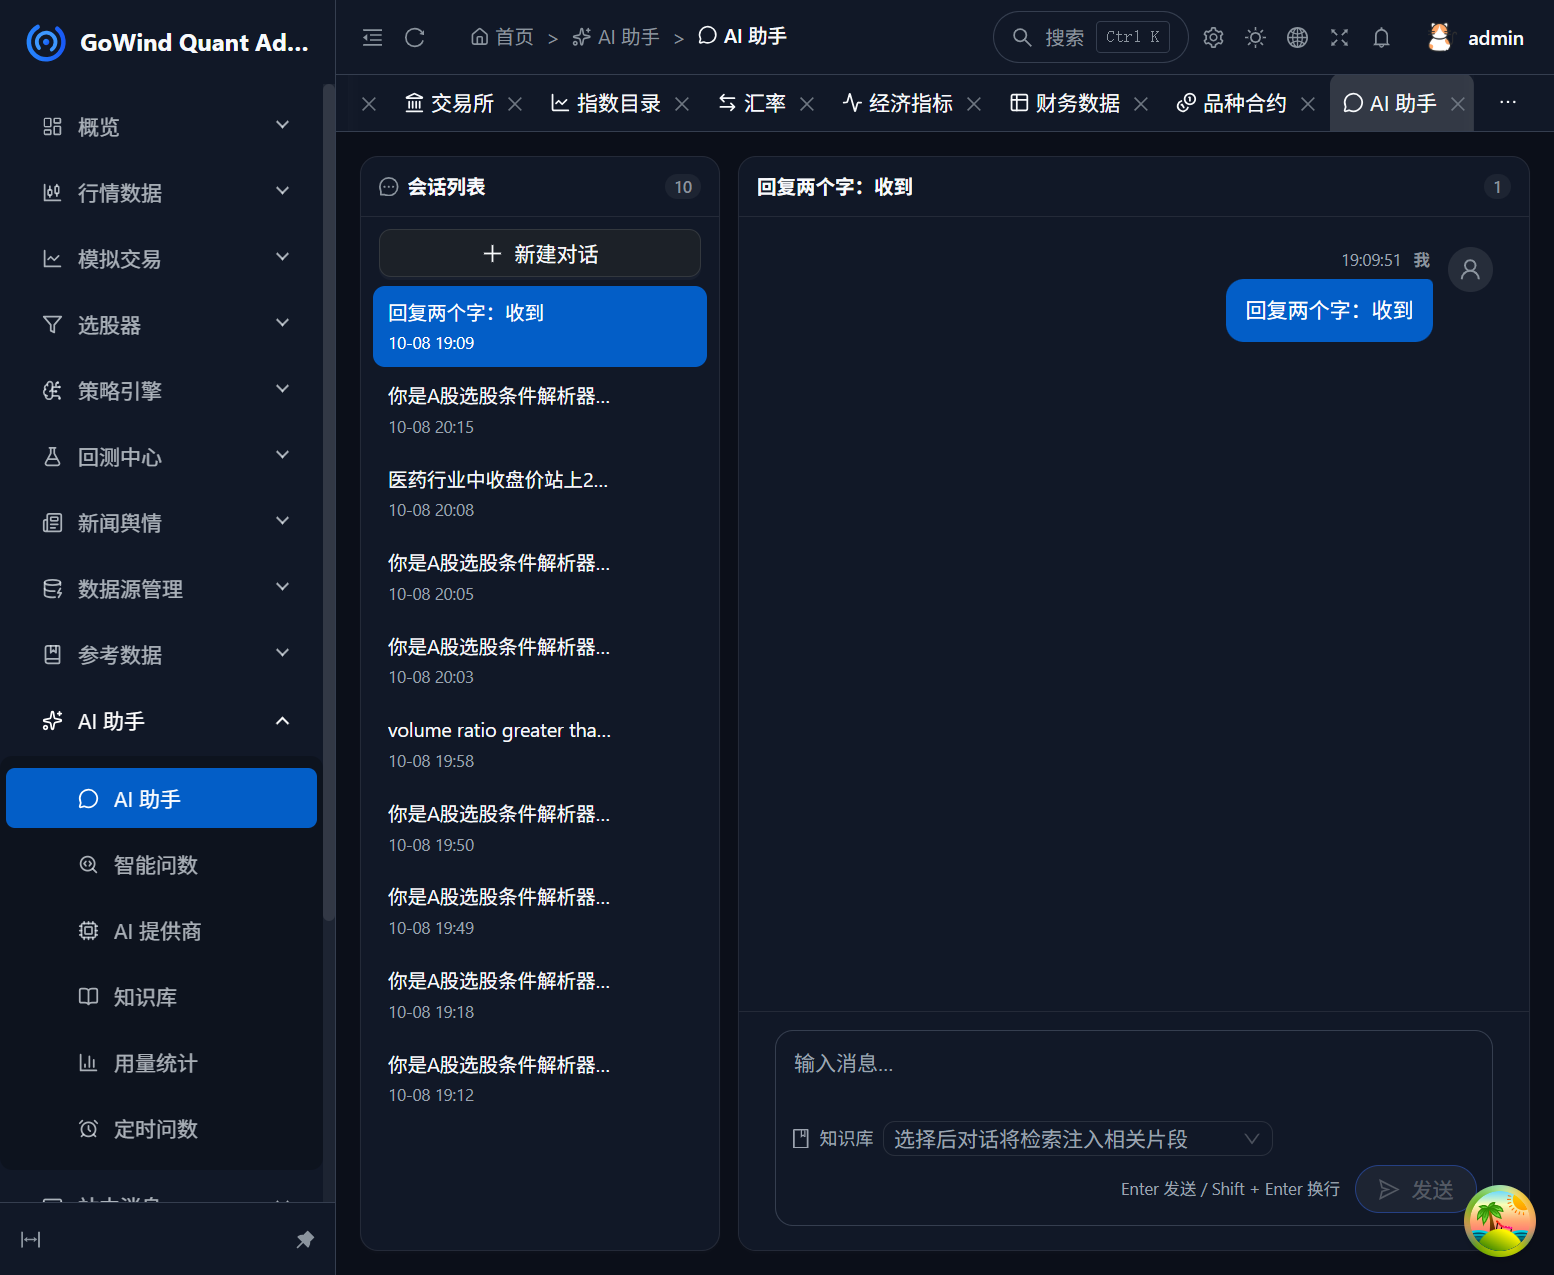 | |
|---|---|
| AI assistant conversation |
Who It's For
- Investment research teams: a unified workspace for data, screening, backtesting, and review — replacing a patchwork of separate tools
- Strategy researchers: a complete path from idea to validation, with AI assistance accelerating strategy iteration
- Multi-instrument/portfolio strategy researchers: evaluate a whole basket of instruments in one cross-sectional pass, with portfolio-level risk and attribution
- Quant education and training: a simulated trading environment under real market constraints — practice without touching real money
Learn More
- Strategy research: the four strategy paradigms the platform supports and the research backing for each — see Strategy Research.
Contact
- WeChat:
yang_lin_bo(please include the note: Quant - Company - Name - Focus) - Email: yanglinbo@gmail.com
- Ecosystem home page: https://www.gowind.cloud